GoPro Drew $20M From Yorkville Three Days Before the Merger Stub Halved
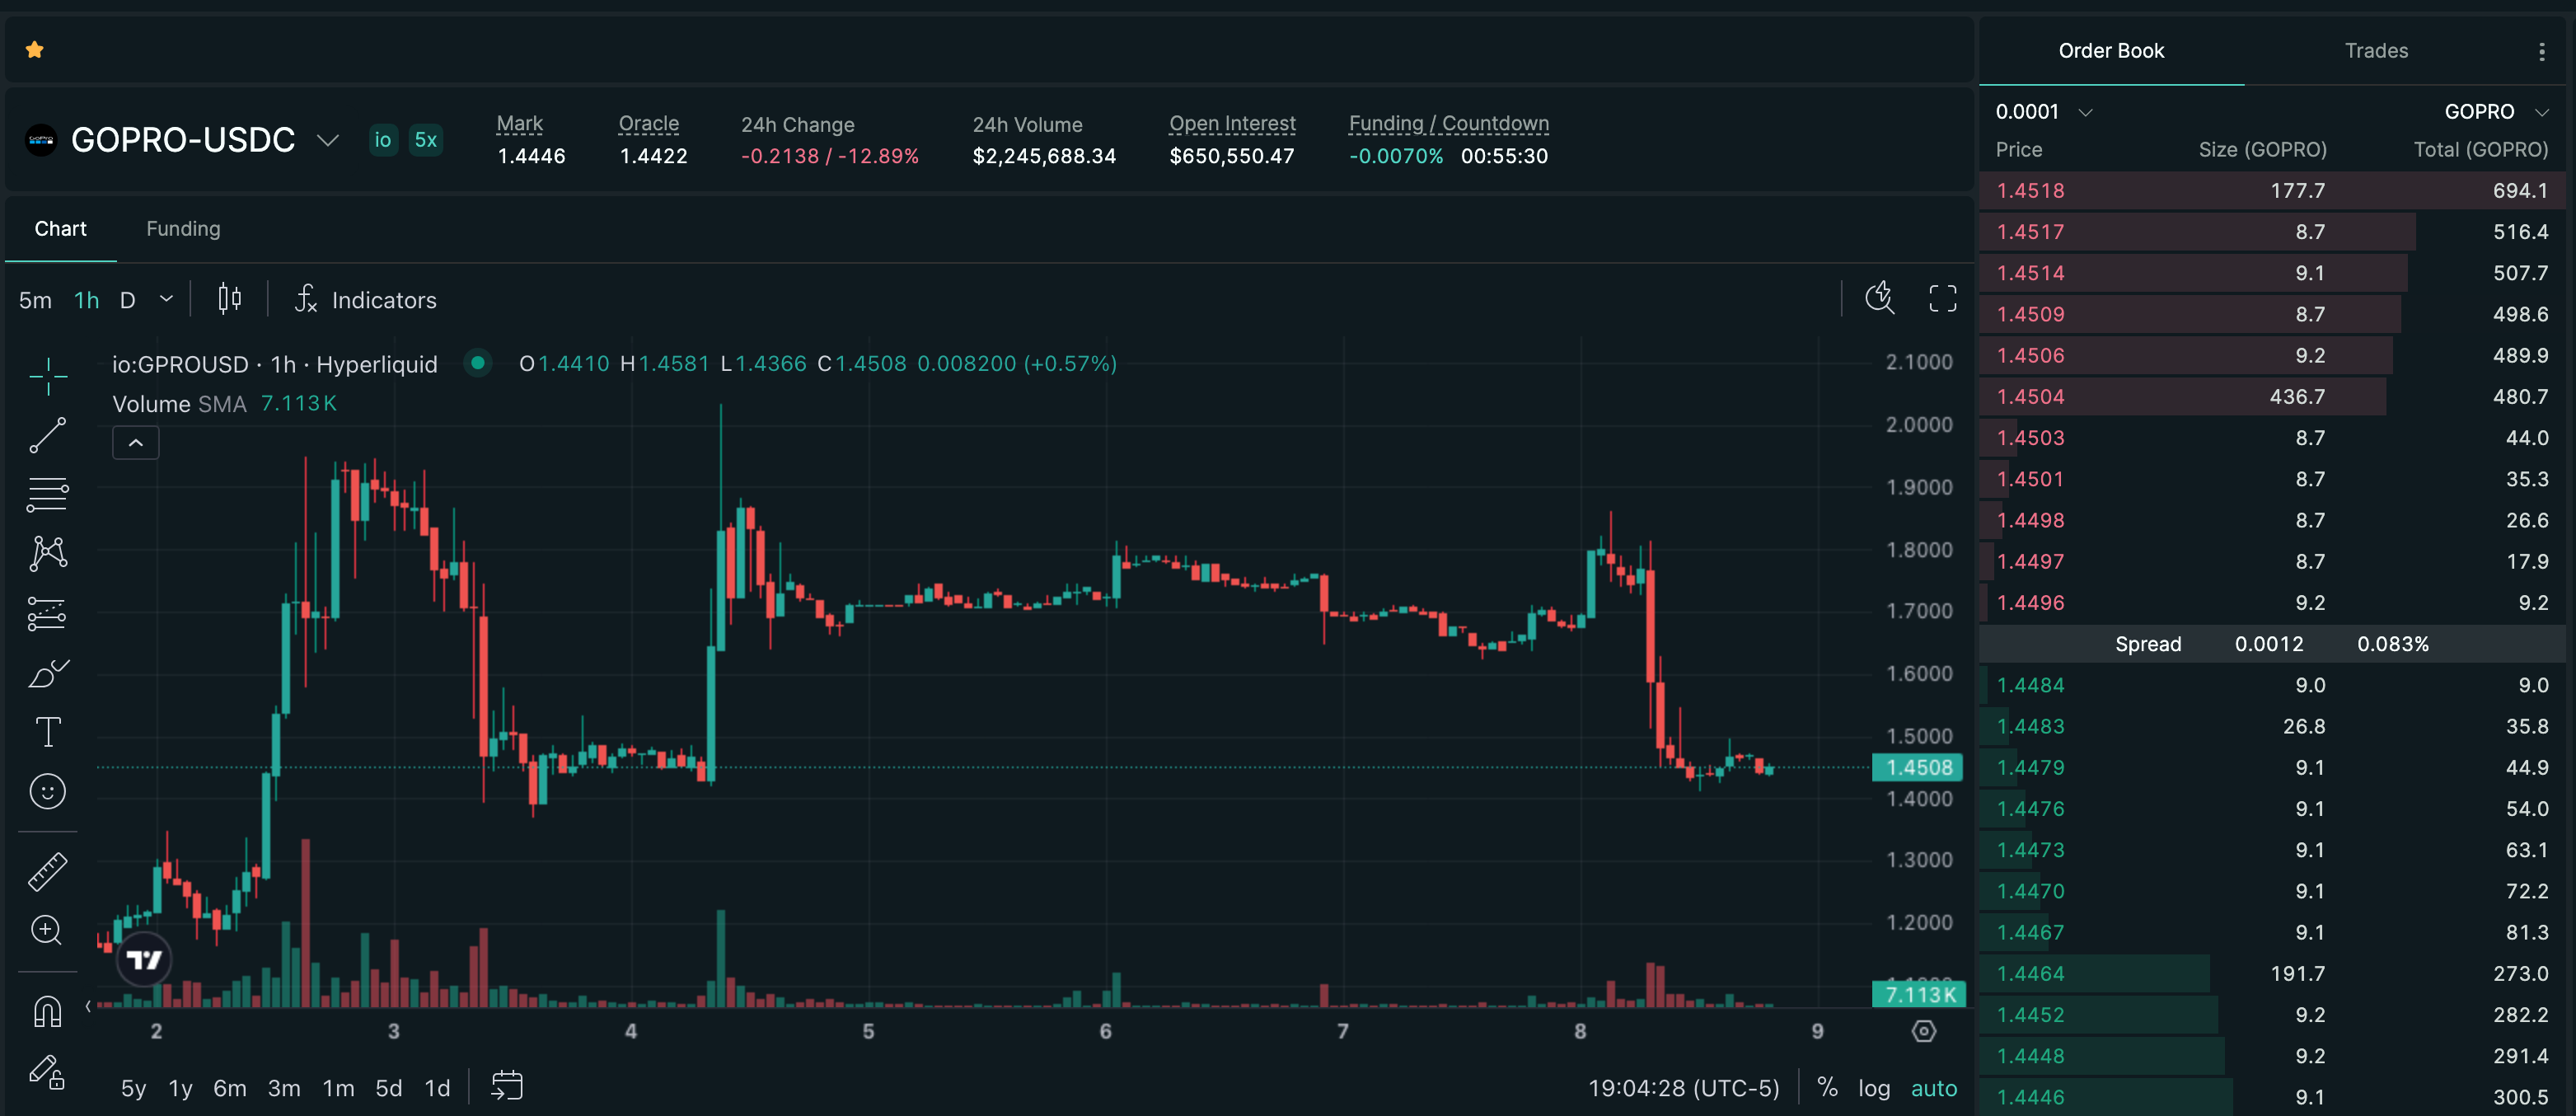
GoPro issued a $20 million floating-conversion debenture to Yorkville on September 8, the third closing under a facility signed in February. The equity closed down 14.41 percent at $1.455 and the io:GPRO perp on Hyperliquid went further, down 21.45 percent over sixteen hours to $1.443. The merger consideration is fixed at $1.14 in cash plus 0.1 share of the surviving corporation, so the entire drawdown lands on the stub. At Friday's price the market valued each Starman share at $5.79. It now values it at $3.03.
Mover Brief
The Filing That Did It
There was no press release on Monday. GoPro's investor relations page still shows one September item, the merger announcement from September 1. What moved the stock was an 8-K filed September 8 carrying items 1.01, 2.03 and 3.02 — new agreement, new debt, new unregistered equity, all at once.
The substance: GoPro issued a $20,000,000 convertible debenture to YA II PN, Ltd. — Yorkville — as the Third Closing under a securities purchase agreement dated February 27, 2026 that authorizes up to $50 million. Yorkville took $25 million at signing. The note carries a 3.00% original issue discount, matures August 26, 2027, and pays no interest unless something goes wrong, at which point the rate steps to 5.00%, or to 18.00% on an uncured default or if conversion shares hit capped levels within six months.
The conversion mechanic is the part that matters. Yorkville converts at its option into Class A common at the lower of $1.35 or 98% of the lowest daily VWAP over the five trading days before conversion, with a floor of $0.1736 and a 4.99% beneficial ownership cap. That is a note whose strike follows the stock down and resets off the lowest print in the window. The 4.99% cap means Yorkville cannot hold a large block, so the structure functionally requires convert-and-sell in slices. Between now and closing there is a seller in this stock whose next conversion price is set by the damage the last one did.
A company four months from a cash merger does not draw the third tranche of a floating-conversion facility unless it needs the cash.
Why Dilution Isn't the Real Problem — the Working Capital Test Is
The instinct on a toxic convertible is to reach for dilution math. That instinct is wrong here, and the reason is worth walking through, because it points at the thing that actually should scare holders.
The merger consideration is fixed per share: each GoPro share converts into $1.14 in cash plus 0.1 of a share of the surviving corporation. It is not an aggregate pot divided by a headcount. New shares created by a Yorkville conversion arrive with their own $1.14 claim and their own 0.1 stub. Mechanically, that dilutes Starman, not the existing holder.
What is not fixed is the cash. The $1.14 is subject to downward adjustment for any net working capital shortfall below a threshold in the merger agreement. That clause was background noise a week ago. It is not background noise once the company draws $20 million of near-dated paper. The debenture matures inside twelve months of a year-end close, so it sits as a current liability against roughly $19.4 million of net proceeds — near-neutral on day one, and negative from there for every dollar burned. This is a business that posted $105 million of Q2 revenue, down 31.3% year over year, and that Morgan Stanley marked to 50 cents in August.
The threshold itself is not in the public summaries, so the size of the risk is unquantifiable from outside. But the direction is not ambiguous, and the market read the filing the same way: the $1.14 is a variable, and Monday was the first hard evidence about which way it varies.
The Stub Repriced by Half in Three Sessions
Strip the cash out and the arithmetic is clean. At $1.443, the perp pays $0.303 above the $1.14 cash. Divide by the 0.1 exchange ratio and the market is marking each surviving-corporation share at $3.03.
On Friday, this desk ran the same calculation at $1.719 and got $5.79. The stub has lost roughly 48% of its implied value in three sessions with no change to the deal terms and no company statement about the business. That is the market re-underwriting what it is being handed: a 10% residual in a combined entity built around Starman's U.S.-made optical transceivers aimed at AI data center, defense and aerospace demand, bolted to a camera business in structural decline. Starman is privately held; there are no public revenue figures. The $5.79 mark was a number for a story. The $3.03 mark is a number for a story with a financing problem attached.
Worth noting what did not change. The vote is still not a real risk — GoPro's dual-class structure gives Class B ten votes a share and leaves Nicholas Woodman with roughly 63% of the voting power, which is why Markiplier's public opposition never mattered arithmetically. The deal is still expected to close by year end subject to regulatory approval. Nothing about deal certainty moved on Monday. The price of the equity piece did.
The Perp Overshot
The io:GPRO perp fell 21.45% over sixteen hours to $1.443 against a 14.41% decline in the underlying to a $1.455 close. The perp printed through the cash close and traded below it.
That gap is the HIP-3 market doing what a thin 5x venue does to a name that just rallied 100%-plus in a week. Longs stacked into a merger-arb setup at $1.70 with leverage, and a filing that reopened the cash-consideration question found them. $2.24 million of 24-hour volume on this specific perp is not deep enough to absorb that in an orderly way — this is the io deployer's market only, not GoPro's consolidated tape.
The reference point going forward is $1.14, and it is now a moving one. Anything the perp trades above that is a bet on Starman; anything it trades below it is a bet the working capital adjustment bites. Yorkville's conversions are the next observable data — each one prints in the resale supplements and each one resets a strike off whatever the low VWAP happened to be.
Sources & Provenance
Citations below are preserved as structured Postgres source rows for this brief.
Citations Preserved
7
Reference links carried forward from the published mover record.
Original Signal
Open source tweetMarket Route
Direct route preserved for readers who want to inspect the tracked Hyperliquid market behind this archive entry.
Already onboarded? Open tracked market- 1GoPro Form 8-K, September 8, 2026 — $20M Yorkville convertible debenture (Third Closing)sec.gov
- 2GoPro press release — Definitive merger agreement with Starman Optical, September 1, 2026prnewswire.com
- 3GoPro Form 424B3 prospectus supplement — merger consideration of $1.14 cash plus 0.1 surviving-corporation sharesec.gov
- 4GoPro 2026 proxy statement — dual-class voting structure and share countssec.gov
- 5TechCrunch — GoPro to be acquired for $285M, will remain a public companytechcrunch.com
- 6Newsshooter — Starman Optical's transceiver business and combined-company strategynewsshooter.com
- 7StockAnalysis — GPRO September 8 close, Q2 revenue decline, Morgan Stanley target cutstockanalysis.com
This content is for informational purposes only and does not constitute financial advice. Trading perpetual futures involves substantial risk of loss.
Trade GPRO on Hyperliquid
Use referral code HIPERWIRE for 4% off trading fees on your first $25M in volume.
Live Market Metrics
Monitor real-time open interest and funding for GPRO.